Book a Demo

Consumer Lending Software Fast Product Rollout

timveroOS is consumer lending software for banks, challenger banks and credit unions. Run personal, auto and installment loans in one installation, and the same team handles 2 to 5 times the volume at flat cost-to-income.

Consumer Lending Software
  • 10x Automated Ops Efficiency
  • 13+ Countries Served Globally
  • 5.0 ★ Verified Client Rating
  • 20+ Lending Products Live
1 The Problem

Why Consumer Lending Teams Hit a Wall With Their Current Stack

Consumer lending moves at the speed of the borrower’s expectation, instant pre-qualification, transparent pricing, frictionless e-sign, hardship handled with empathy. The systems most teams are running on weren’t built for any of that. They were built to issue a loan, then patched ten times to do everything else. Originating a single unsecured consumer loan costs the industry $150 to $400 all-in, and labour is 55 to 70% of it. That is the line timveroOS moves.

  • SaaS Lending Platforms Hit a Customization Ceiling

    Your underwriting model evolves. A new affordability rule from the regulator. A bundled installment product the merchant wants live in two weeks. SaaS roadmaps don’t move on your timeline, and per-loan or per-seat fees scale faster than your portfolio.

  • Custom Builds Take 12–18 Months to First Loan

    Building from scratch means writing the underwriting engine, e-sign workflow, GL posting logic, bureau integrations, servicing cycle, and hardship state machines, before you onboard a single borrower. Most teams underestimate the cost by 2× and ship 9 months late.

  • Legacy LMS Can’t Pass a Modern Compliance Review

    CFPB Reg Z, FCA Consumer Duty, IFRS 9 / CECL provisioning, all require explainable decisions, version-controlled policies, and audit-ready trails. Spreadsheet overrides and undocumented vendor logic do not survive a regulator walkthrough.

2 Solution

End-to-End Consumer Lending Lifecycle, Configured to Your Policies

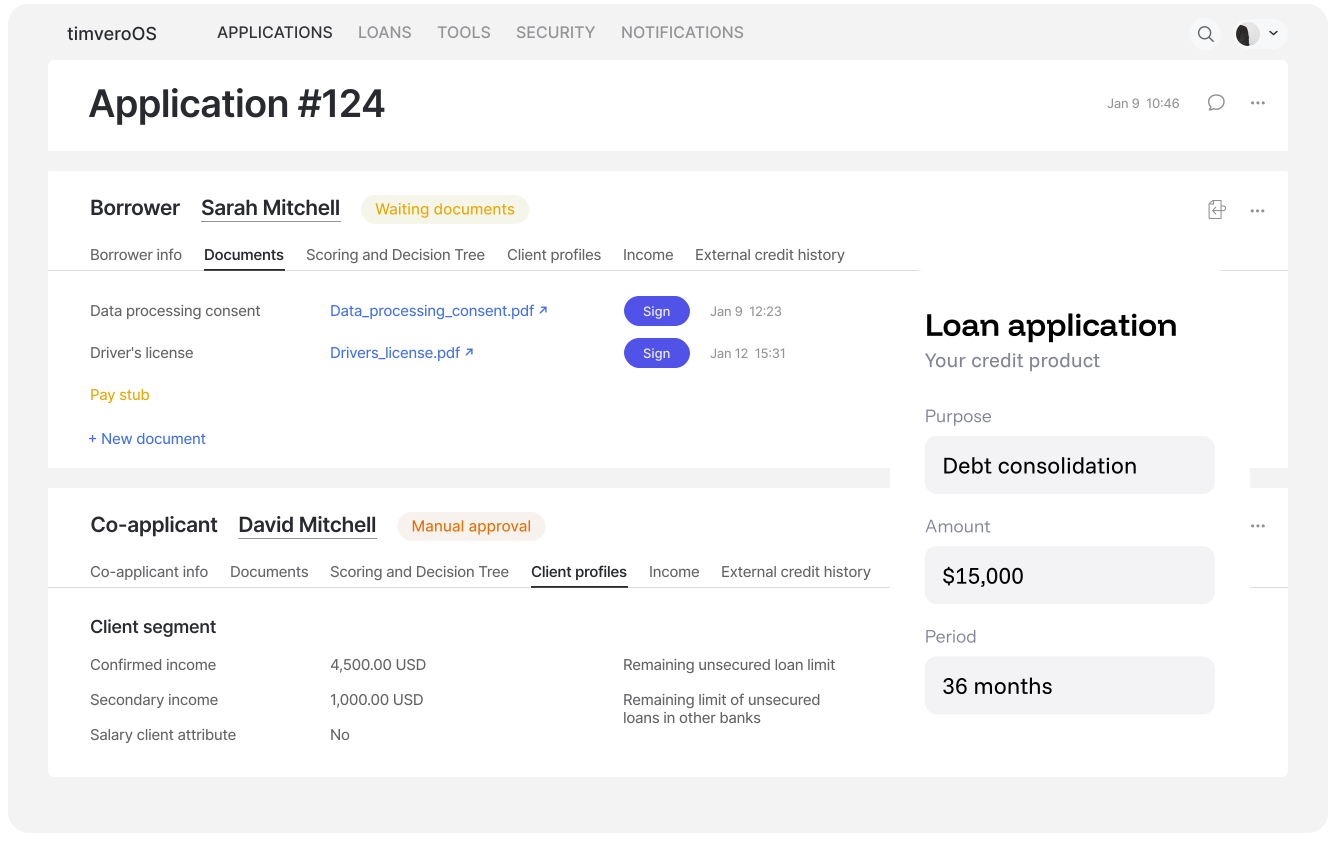
timveroOS is a lending solution built on a Building Platform: building blocks covering the consumer-lending lifecycle that you configure in the admin panel and reshape via a Java/Spring Boot SDK. Applicants, accounts, devices, bureau data, assemble personal loans, debt consolidation, BNPL, or POS without rebuilding the primitives.

  • Instant Onboarding With Built-in Compliance

    Borrowers complete KYC/AML in minutes through digital onboarding. Identity, income, and device signals are verified automatically; bureau and open-banking data flow into affordability and DTI calculations. Exceptions route to governed overrides, risk teams stay in control without slowing the flow.

  • Approvals You Can Explain to Risk and Regulators

    Bureau files plus transaction-level income features model true affordability. Credit cutoffs, DTI ratios, and offer waterfalls are encoded as policies-as-code, not buried in vendor logic. Every “yes” or “no” carries reason codes for applicants, analysts, and regulators alike.

  • Compliant Offers and Clean Disbursements

    timveroOS assembles the offer document, captures e-sign with full audit trail, posts the loan to your GL, and triggers disbursement through your payment rails, all compliance attestations attached. Faster funding for the borrower; a cleaner book for finance.

  • Service Borrowers at Scale, Manage Hardship With Empathy

    Automated billing, payment matching, fee posting, and collections, with policies-as-code for hardship, restructuring, and write-off logic. Borrowers self-serve through portals; agents handle exceptions through a unified workspace; configurable workflows keep restructuring compliant.

3 Customer Stories

Consumer Lenders Building on timveroOS

Multi-country consumer lending products launched and scaled on the Building Platform, automated decisioning, lower TCO, faster time-to-launch.

98% Of Credit Decisions Automated
7 mo From Kickoff to Production

How Finom Automated 98% of Consumer-Lending Operations on timveroOS

Traditional banking systems quoted 24 months in-house and a seven-figure budget. We built on timveroOS, the Building Platform supplied 80% of the credit infrastructure, and timveroAI handled the configuration to our spec. The result: a fully automated lending operation across multiple regulatory environments, deployed at a fraction of the cost and time of a conventional core.

Finom Lending Team

EU EMI Serving 200K+ SMEs Across 4 Countries

Read Full Story
  • 8× Faster Origination

    AMIO Bank

    After three failed attempts with two vendors, AMIO launched guarantor lending on timveroOS in 6 months, 8× faster, 95% automation.

    Read Full Story
  • 90% Legacy Platform Cost Savings

    Cartiga

    US litigation-finance lender deployed $1.6B+ in advances. 8-week MVP, 90% lower TCO vs the prior platform.

    Read Full Story
timveroAI

timveroAI Studio: The Default AI for Lending Teams

Your lending owner knows which change would lift approvals in the segment she watches. With timveroAI Studio she describes it in plain language, sees it built in the same session and corrects it on the spot. Engineers and risk review a clean, versioned draft, and only the approved logic runs, across origination, servicing and collections.

Explore timveroAI
  • From Intent to Build

    Pricing rules, eligibility conditions and document requirements described in plain language become a working draft.

  • Whole Lifecycle Covered

    Change origination steps, servicing workflows and collections cadences, not only credit rules.

  • Nobody Loses the Keys

    Engineers stay the gatekeepers of production, reviewing a correct draft instead of translating a vague ticket.

  • Exception Agents Next

    Agents that prepare stalled manual cases for a human decision are targeted for Q4 2026.

  • 80% Pre-Built Lending Core
  • 3 wks Signing to Product Launch
  • ~7.8x Faster Delivery vs In-House
  • <1 wk Initial Up-and-Run on Skeleton
4 Why timveroOS

Why Consumer Lenders Choose timveroOS

  • Affordability and Pricing Encoded as Policy

    Turn your lending rules into code: affordability checks, DTI ratios, APR ranges, fee structures. Every decision is explainable, every version is stored, without custom plumbing. This supports compliance, accelerates product changes, and removes dependency on hidden vendor logic.

  • Your Bureau, Open-Banking, and Fraud Data: Natively Connected

    Whether your bureau is Equifax, Experian, or TransUnion; your open-banking provider Plaid, TrueLayer, or Tink, data flows through governed, auditable pipelines designed for explainability. One source of truth for risk, operations, and compliance, owned in your code, not reconciled between vendor systems.

  • Control Your Stack, Control Your Costs

    Deploy on your cloud or on-prem. Open APIs and a Java/Spring Boot SDK let your teams extend flows without waiting on vendor releases. Costs are predictable, free of per-loan or per-seat traps. You keep ownership of data, code, and product direction while scaling on your terms.

  • Entity-Centric Data Model for Real Consumer Borrowers

    Most lending systems were built around a single applicant and a single loan. Real consumer lending needs more, co-applicants, joint accounts, guarantors, multiple devices. timveroOS models all of these as first-class entities with full relationship history, visible to underwriting, servicing, and collections.

5 Comparison

An Easy Choice Between SaaS Speed and Custom Control

AI brings the speed; the Building Platform brings the trust, bespoke lending systems for regulated lenders without forcing a choice between fast and compliant. SaaS launches quickly but limits flexibility. Custom builds offer control but ship in 24 months in-house. timveroOS delivers all three.

SaaS Solutions

Pros

  • Fast initial go-live
  • Lower upfront cost
  • Prebuilt workflows

Cons

  • Limited policy/UX flexibility
  • Vendor roadmap & data custody constraints
  • Volume/per-seat fees escalate TCO

Custom Development

Pros

  • Full control of code and UX
  • Tailored integrations & data model
  • No vendor lock-in

Cons

  • 24-month in-house delivery risk
  • High build & maintenance cost
  • Talent/knowledge concentration risk
Lending solution on a Building Platform
6 The Resolution

AI brings the speed. The Building Platform brings the trust.

Together, they deliver bespoke lending systems for regulated institutions, without forcing you to choose between fast and compliant.

  • Speed

    3 weeks live with timveroAI

  • Trust

    Policies-as-code with full audit trail

  • Together

    One Building Platform, no architecture trade-off

7 Integrations

Your Consumer-Lending Stack: Integrated as Building Blocks

We know the vendors that matter for US, UK, and EU consumer lending. During deployment, your specific stack is wired into the Building Platform as native, governed building blocks, owned in your code, not marketplace adapters with per-call fees.

  • Data Sources

    Whether your bureau is Equifax, Experian, TransUnion, CIFAS, SCHUFA, or BKR, the credit data is integrated natively into your underwriting. Open-banking feeds (Plaid, TrueLayer, Tink) wired into affordability and DTI logic. Alternative data sources slot in as additional building blocks.

  • Identity & Risk

    KYC/AML providers (Onfido, Jumio, Sumsub, ComplyAdvantage) integrated as governed building blocks, not vendor black-box logic. Fraud and device signals (Sardine, Sift, ThreatMetrix) feed directly into your decisioning flow. Sanctions and PEP screening as native checks, not marketplace add-ons.

  • Money Movement

    Payment rails wherever you operate (ACH, RTP, FedNow, Zelle in the US; Faster Payments in the UK; SEPA across the EU) integrated directly into servicing flows. Card networks for disbursement and collection. Borrower communications via Twilio, SendGrid, or your existing notification provider.

  • Core Systems

    Open APIs to any core banking system: Temenos, Mambu, Finastra, Fiserv, your in-house core, or a legacy mainframe. GL posting integrates with your accounting platform of record. The Open SDK turns each connection into a first-class building block, surfaced in your admin panel.

8 FAQ

Common Questions About Consumer Lending Software

How timveroOS handles consumer-lending essentials: deployment, compliance, decisioning, integrations, and pricing.

Talk to Sales
  • What is consumer lending software?

    Consumer lending software runs the end-to-end lifecycle of a consumer credit product: digital onboarding, KYC/AML, underwriting and affordability, e-sign and disbursement, servicing, hardship, and collections. Modern platforms add explainable decisioning, regulator-ready audit trails, and integrations to bureaus, open-banking feeds, and payment rails. timveroOS delivers all of this as a lending solution built on a Building Platform, meaning the lifecycle works out of the box and remains shapeable in code at the architectural level.

  • How is timveroOS different from SaaS consumer lending platforms?

    SaaS platforms are fast to start but cap your customization at the vendor’s roadmap and store your data in their multi-tenant environment. timveroOS is a lending solution built on a Building Platform: you deploy in your own cloud or on-prem, you own the code and the data, and your team extends building blocks via a Java/Spring Boot SDK when your credit product needs something the platform doesn’t yet support. Pricing is portfolio-tiered, no per-loan or per-seat surcharges that scale faster than your business.

  • How long does it take to launch a consumer lending product on timveroOS?

    Typical implementation is 3 weeks, compared to 9 months on a multi-vendor assembly and 24 months in-house. The Building Platform supplies 80% of the consumer-lending stack out of the box, and timveroAI, our controlled, RAG-grounded implementation agent built on Claude Code , composes the remaining 20% of the configuration, with human-in-the-loop approval and shadow-run validation before production.

  • Does timveroOS integrate with our credit bureau, KYC provider, and payment processor?

    Yes. timveroOS doesn’t ship with a fixed marketplace of integrations, and that’s the point. Every connector your consumer-lending operation needs is implemented as a first-class building block during deployment, native to your code and governed by your policies-as-code. When your team adds a new vendor down the road (a regional bureau, a niche fraud provider, your existing core banking) the Open SDK turns it into another building block, and timveroAI typically composes the integration in days. Your stack stays yours.

  • Can timveroOS be deployed on-premises?

    Yes. The Building Platform is deployment-agnostic, public cloud, private cloud, on-premises, or hybrid. Your data, your infrastructure, your release schedule. This is essential for regulated lenders who can’t accept multi-tenant SaaS for data sovereignty or compliance reasons, and for teams who want their lending stack to outlast any vendor relationship.

  • What consumer loan types does timveroOS support?

    Personal loans, debt consolidation, refinancing, BNPL, POS installments, auto loans, retail and merchant installments, microfinance, payday and short-term credit, and lines of credit. Because the Building Platform’s building blocks (entities, state machines, GL posting, integrations) are product-agnostic, you can launch new consumer-credit products without rebuilding the underlying primitives.

  • How does timveroAI accelerate consumer lending implementation?

    timveroAI is a controlled, RAG-grounded implementation agent built on Claude Code, trained on the Building Platform’s source code and past consumer-lending deployments. You describe a business requirement (a new affordability rule, a hardship workflow, a checkout-installment product) and timveroAI composes the matching building blocks: entities, state machines, forms, integrations, GL posting logic. Every change is validated in shadow-run mode and approved by a senior developer before production. Result: 80% of the build ships pre-built, timveroAI composes the remaining 20%, and launch runs 3 weeks.

  • What compliance frameworks does timveroOS support for consumer lending?

    US: CFPB regulations including Reg Z (TILA), FCRA, ECOA. UK: FCA Consumer Duty, Consumer Credit Act, FCA SYSC. EU: PSD2, SCA, GDPR. Provisioning: IFRS 9 and CECL building blocks. The Building Platform’s policies-as-code, immutable audit log, and explainable decisioning are designed for transparent regulator review, a regulator walks through any decision with full reason codes and version history, not vendor black-box logic.

Ready to Own Your Consumer Lending Stack?

Join lenders managing $5.5B+ on timveroOS across 13+ countries. Launch your next consumer-lending product on a Building Platform that lets your team configure day-to-day operations and reshape the architecture itself when your business model requires it. 3-week implementation, no per-loan fees, your code and your data.